A duplicate entry in an ITR turned into an Rs 81 lakh tax addition.
An assessee was a partner in a firm engaged in agricultural activities.
His share of profit from the firm was around Rs 81 lakh, which he correctly reported as his share of partnership profit.
But while filing his ITR, he mistakenly reported the same Rs 81 lakh again as agricultural income.
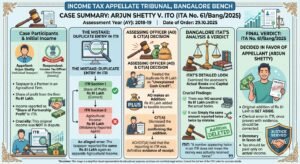
The Assessing officer treated the amount as an unexplained cash credit and made an addition of Rs 81 Lakh.
The matter reached the Bangalore ITAT, which looked into the assessee’s actual books and capital accounts.
There was no second Rs 81 lakh credit in the books.
It was simply the same amount reported twice in the ITR by mistake.
The Tribunal deleted the addition and said a number appearing twice in an ITR doesn’t mean the money was actual received twice.