Apparently, there seems to be a new GST calculation methodology:
Step 1: Look at the Balance Sheet.
Step 2: Find “Sundry Creditors.”
Step 3: Assume every creditor has remained unpaid for more than 180 days.
Step 4: Take the entire closing balance of creditors.
Step 5: Apply 18% GST.
Step 6: Issue a notice.
The reasoning?
“Payment has not been made within 180 days. Therefore, the entire ITC relating to sundry creditors has to be reversed and GST is payable.”
And the most interesting part?
The SCN itself says that once the taxpayer furnishes the creditor-wise details, the department will modify the figures.
So, what exactly is the approach here?
No detailed analysis.
No transaction-wise verification.
No attempt to understand the nature of the creditors.
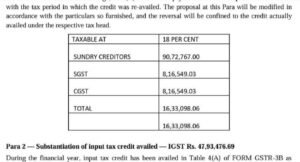
Just pick a figure from the Balance Sheet, create a tax demand on the basis of assumptions, add a reason somehow, and issue a notice.
And if the taxpayer later provides the actual details, the figures can be modified.
Is this really how GST scrutiny is supposed to work?
what do you think..