First of all, start tracking your daily expenses for at least four weeks. After that, take a pause for a few days and review those four weeks of expenses. Look for costs that could have been avoided, things that were not necessary at the moment, and items that could have been postponed.
For example, having multiple monthly OTT platform subscriptions is often unnecessary. If you enjoy watching OTT content, you can keep just one subscription. Alternatively, if you can share or arrange access through friends or colleagues, you can do that so you don’t have to pay for any OTT subscriptions at all.
Similarly, if you have multiple credit cards and use them for unnecessary spending, you should close them. You can keep just one card for emergency use.
If you only go to the gym a few days a month but have bought a full-year membership, you can cut down on that too. You can convert it to a monthly plan so that if you stop going in between, your money for the entire year does not go to waste.
If you have any paid, unused app subscriptions—like astrology or dating apps—that you do not need every month, you can close those as well. This will save you both time and money.
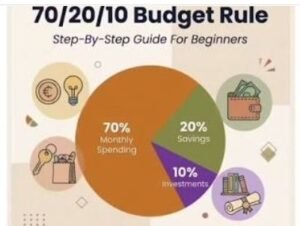
Finally, you can create a budget rule for your monthly income using the 70/20/10 formula. In this rule, you can use 70% of your income for your daily and monthly expenses. From the remaining 30%, you can save and invest 20% into a good equity mutual fund, and save 10% invest in emergency fund, such as a Fixed Deposit (FD), which will provide you with financial support during emergencies.